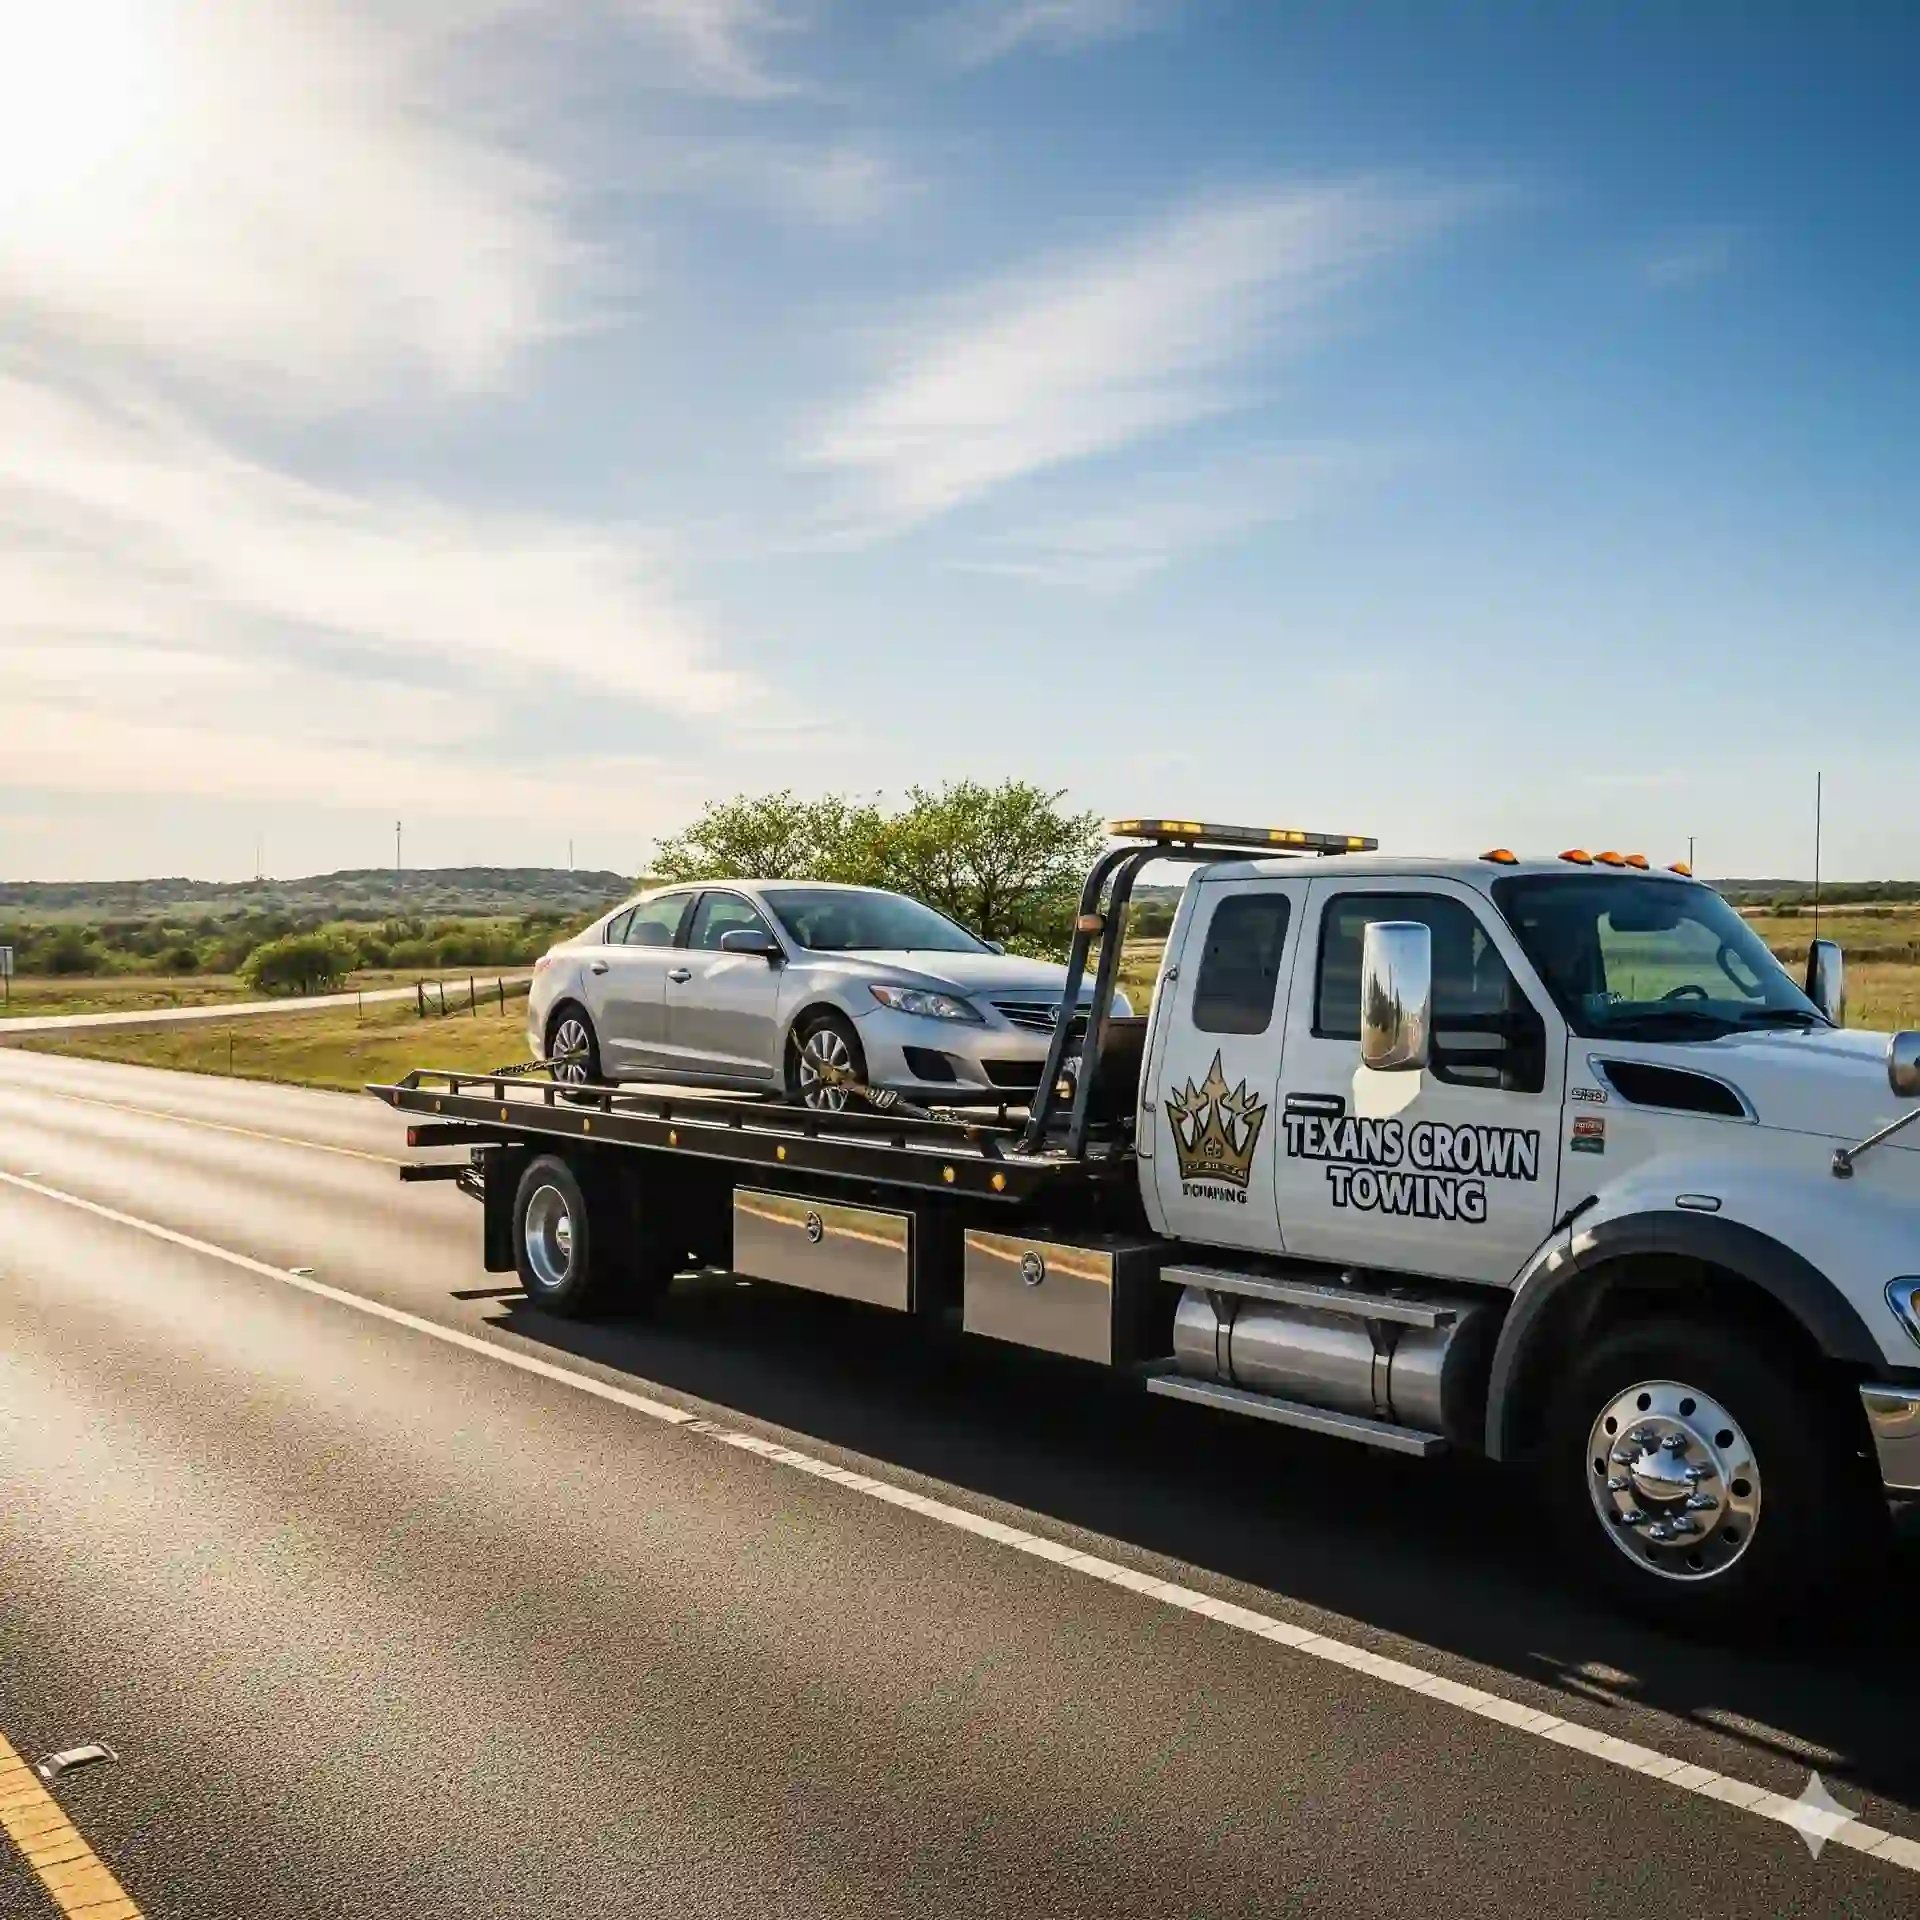
Tow truck operators face some of the highest insurance costs in the automotive industry — and for good reason. Towing involves constant road exposure, handling other people's vehicles, operating heavy equipment in dangerous roadside conditions, and storing vehicles that don't belong to you. The right insurance program protects your business from the significant financial risks inherent in towing operations.
Why Tow Truck Insurance Is Different
Standard commercial auto insurance doesn't work for tow trucks. Towing operations involve unique exposures that require specialized coverage forms:
Need a quote? Get an instant garage liability quote here — most businesses are quoted in under 60 seconds with same-day certificates available.
- On-hook liability: You're responsible for vehicles while they're attached to your wrecker
- Roadside exposure: Operating on highways and in traffic creates elevated accident risk
- Storage liability: Vehicles in your yard are your responsibility
- Heavy equipment: Wreckers, rollbacks, and rotators are expensive to repair and replace
- Regulatory requirements: States mandate specific minimum coverages for tow operators
Tow truck insurance is a specialized product offered by carriers who understand these unique exposures and have the claims expertise to handle towing-specific losses.
Essential Coverages for Towing Companies
1. Commercial Auto Liability (Garage Liability)
Garage liability or commercial auto liability covers bodily injury and property damage caused by your tow trucks while operating on the road. This is the foundation of any towing insurance program and is required by every state. It covers:
- Accidents caused by your tow trucks
- Injuries to third parties from your towing operations
- Damage to other vehicles, property, and infrastructure
Recommended limits: $1,000,000 CSL minimum for most towing operations. Many motor clubs and law enforcement rotation lists require $1M or higher.
2. On-Hook / In-Tow Coverage
On-hook coverage (also called in-tow coverage) protects vehicles while they are physically attached to your wrecker and in transit. If the vehicle being towed is damaged during the tow — whether from an accident, improper hookup, road debris, or equipment failure — on-hook coverage responds.
Key considerations:
- Coverage limits should reflect the maximum value of vehicles you tow
- If you tow luxury vehicles, ensure limits are adequate ($100K+ per vehicle)
- Some policies have per-occurrence limits vs. per-vehicle limits — understand the difference
- Improper hookup damage may or may not be covered depending on policy language
Recommended limits: $100,000–$150,000 per vehicle for general towing; $200,000+ if you regularly tow luxury or high-value vehicles.
3. Garagekeepers Insurance (Storage Yard)
If you operate a tow yard or storage facility, garagekeepers insurance covers damage to stored vehicles from fire, theft, vandalism, weather, and other perils while they are in your custody at the yard. This is separate from on-hook coverage, which only applies while vehicles are being towed.
Recommended limits: Based on the maximum number and value of vehicles stored at any one time. A yard holding 50 vehicles averaging $15,000 each needs at least $750,000 in garagekeepers coverage.
4. Physical Damage (Your Trucks)
Physical damage coverage protects your own tow trucks against collision damage, theft, fire, vandalism, and weather. Given the high cost of tow trucks ($50,000–$500,000+ for heavy-duty rotators), this coverage is essential for protecting your capital investment.
- Comprehensive: Covers theft, fire, vandalism, weather, falling objects
- Collision: Covers damage from accidents regardless of fault
Typical deductibles: $1,000–$5,000 per vehicle depending on truck value and premium budget.
5. Workers' Compensation
Tow truck operators face elevated injury risks: roadside accidents, being struck by passing vehicles, back injuries from winching, and exposure to hazardous conditions. Workers' compensation covers medical expenses and lost wages for injured employees.
Towing operations typically fall into class code 7219 (Trucking NOC) or 8385 (Auto Service), with rates ranging from $5.00–$12.00 per $100 of payroll depending on the state and loss history.
6. Cargo / Motor Truck Cargo
For towing companies that also transport vehicles on rollbacks or car carriers, motor truck cargo coverage may be needed in addition to on-hook coverage. Cargo coverage applies to vehicles being transported as freight rather than towed.
State Requirements for Tow Truck Insurance
| State | Min. Liability (Lower Class) | Min. Liability (Upper Class) | On-Hook Required? | Garagekeepers Required? |
|---|---|---|---|---|
| Florida | $50,000 CSL (26K–35K lbs) | $300,000 CSL (44K+ lbs) | Yes ($50K min) | Yes (if storage yard) |
| Texas | $300,000 CSL (consent/private property) | $500,000 CSL (incident mgmt) | Yes ($50K min) | Recommended |
| Georgia | $100,000 CSL | $300,000 CSL | Recommended | Recommended |
| North Carolina | $300,000 CSL | $300,000 CSL | Recommended | Recommended |
| Oklahoma | $100,000 CSL (Class G/AA) | $300,000 CSL (Class AA-TL) | Yes ($50K–$150K) | Yes ($50K–$150K) |
Note: These are state minimums. Motor club contracts, law enforcement rotation lists, and commercial contracts typically require $1M+ in liability coverage.
How Much Does Tow Truck Insurance Cost?
Tow truck insurance costs vary significantly based on fleet size, truck types, driver records, claims history, and state. Here are typical annual ranges:
| Operation Size | Trucks | Estimated Annual Premium |
|---|---|---|
| Owner-operator (1 truck) | 1 | $8,000–$15,000 |
| Small fleet | 2–5 | $15,000–$45,000 |
| Medium fleet | 6–15 | $45,000–$120,000 |
| Large fleet | 15+ | $120,000+ |
These estimates include liability, on-hook, physical damage, and garagekeepers. Workers' comp and umbrella are additional.
Tips for Reducing Tow Truck Insurance Costs
- Driver screening: Clean MVRs are the single biggest factor in towing insurance rates. One driver with a DUI or multiple violations can increase your entire fleet premium by 30–50%.
- Dashcams: Many carriers offer discounts for fleets with forward-facing cameras. Cameras also help defend against fraudulent claims.
- Safety training: Documented WreckMaster or similar certification training can reduce premiums.
- Higher deductibles: Increasing physical damage deductibles from $1,000 to $2,500 can save 15–25% on that coverage.
- Claims management: Maintaining a clean loss history is critical. One or two large claims can make you difficult to insure.
- Work with a specialist: General insurance agents often can't access the specialized towing markets. An agent who focuses on tow truck insurance has access to carriers that understand and want this business.
Getting Covered
Tow truck insurance is a specialized market, and not every carrier writes it. The carriers that do specialize in towing understand the unique risks and can offer coverage forms tailored to your specific operation — whether you're a single-truck operator doing roadside assistance or a large fleet handling heavy-duty recovery and law enforcement rotations.
At DealerLiability.com, we work with multiple A-rated carriers experienced with tow truck insurance. We can help you build a complete program covering liability, on-hook, garagekeepers, physical damage, and workers' comp — all at competitive rates. Get a free quote and see what we can do for your towing operation.
Disclaimer: State requirements, premium estimates, and coverage descriptions in this article are general in nature and based on publicly available information as of 2026. Actual requirements, rates, and coverage terms vary by state, carrier, and individual risk factors. Always verify current state requirements with your state's regulatory agency and consult with a licensed insurance agent. This article does not constitute insurance or legal advice.
Kevin A. Smith
Kevin specializes in commercial insurance for automotive businesses — dealers, repair shops, towing companies, and garages — across FL, TX, GA, NC, SC, OK, NM, and UT. He works with 100+ A-rated carriers to find the right coverage at the right price.
View all articles by Kevin