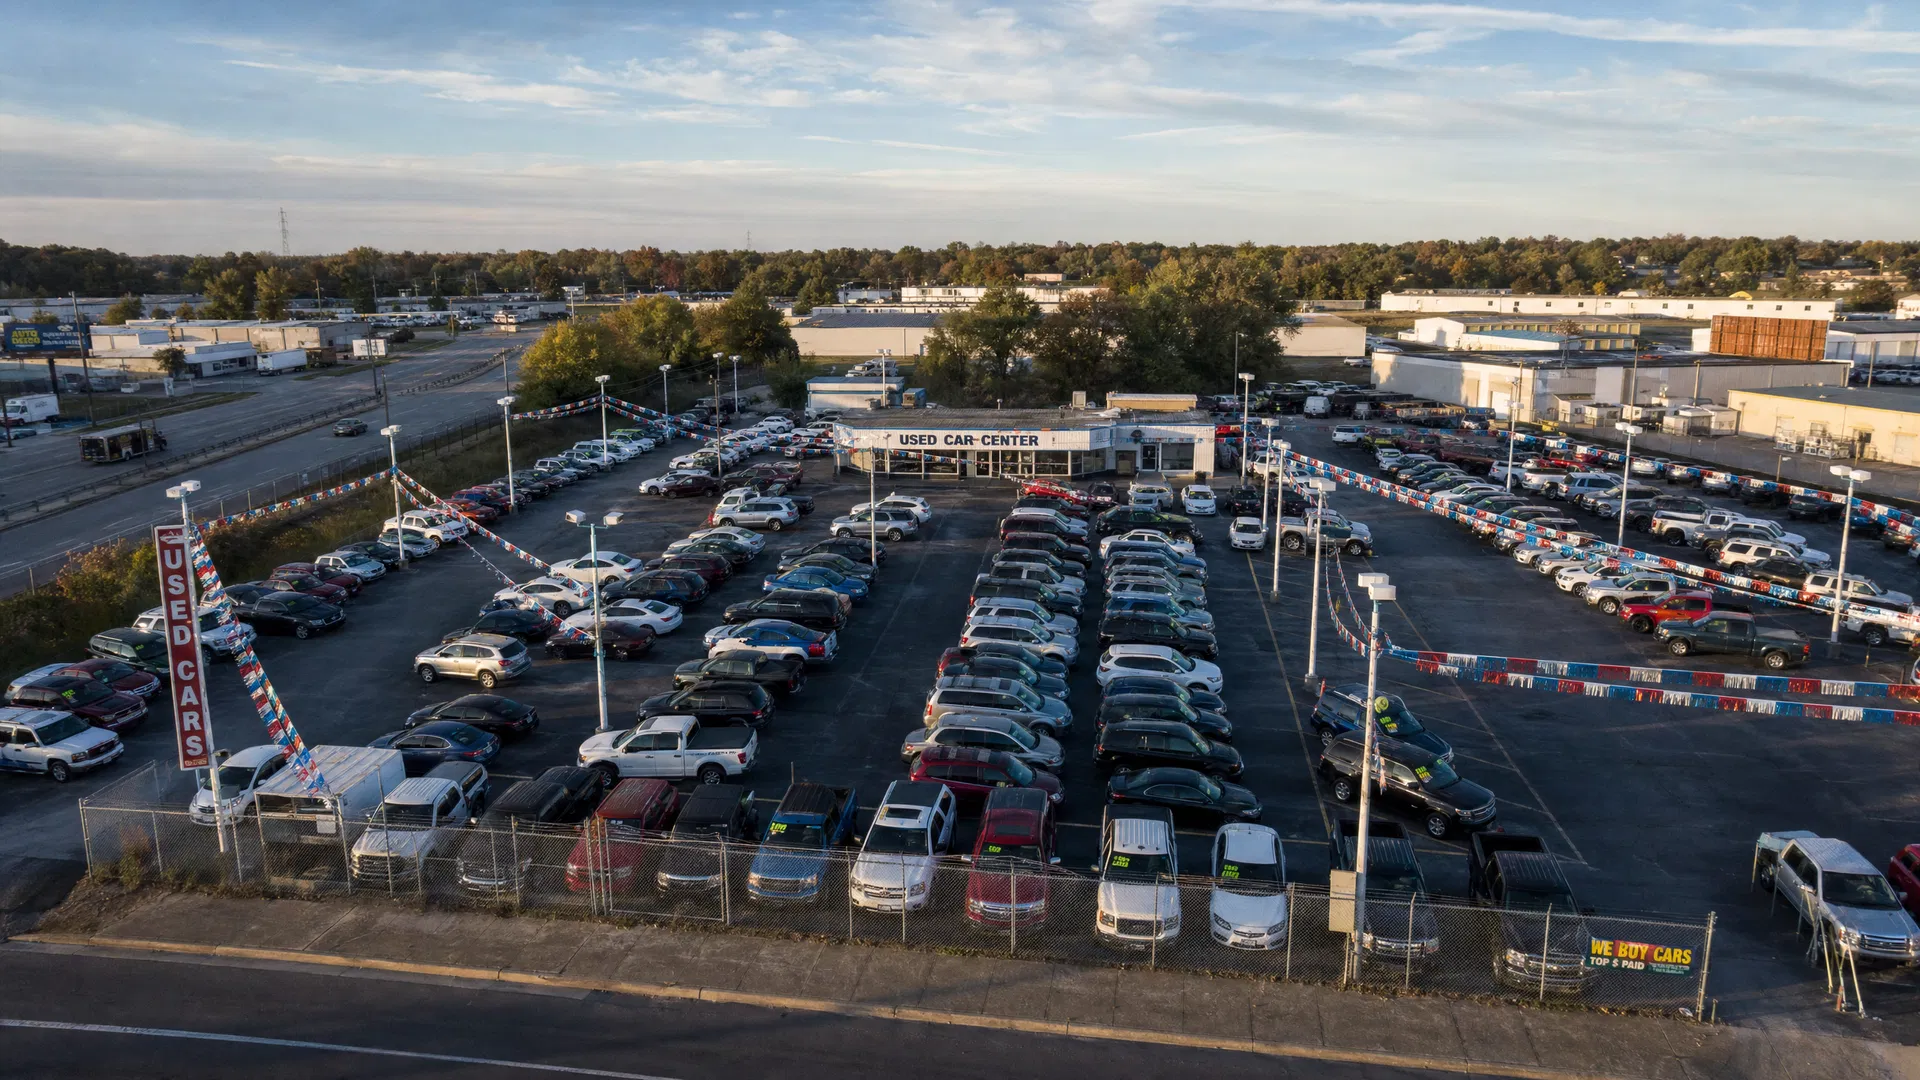
Dealers open lot (DOL) insurance covers physical damage to your vehicle inventory while it's on your lot, in transit, or at auction. If you have vehicles on your lot — whether 10 or 1,000 — DOL protects them from hail, theft, fire, flood, vandalism, and collision damage.
Need DOL coverage? Get an instant quote here — we can bundle DOL with your garage liability for the best overall rate.
What Does Dealers Open Lot Insurance Cover?
DOL insurance covers physical damage to vehicles you own for the purpose of sale. Covered perils include:
- Hail damage — the #1 cause of DOL claims, especially in Texas, Oklahoma, and the Southeast
- Theft — vehicles stolen from your lot (including catalytic converter theft)
- Fire — vehicles damaged or destroyed by fire on your premises
- Flood — vehicles damaged by rising water, storm surge, or heavy rain
- Vandalism — intentional damage to your inventory by third parties
- Collision — vehicles damaged while being moved on your lot or during test drives
- Wind & tornado — vehicles damaged by severe weather events
- Falling objects — trees, debris, or building materials damaging vehicles
What Dealers Open Lot Does NOT Cover
Understanding exclusions is just as important as understanding coverage:
- Customer vehicles — vehicles belonging to customers (trade-ins not yet titled to you, service vehicles) require garagekeepers insurance
- Mechanical breakdown — engine failure, transmission problems, or normal wear and tear
- Vehicles in transit by common carrier — may require separate inland marine coverage
- Intentional damage by you or employees — fraud or intentional acts are excluded
- Vehicles not on your inventory list — some policies require you to report inventory; unreported vehicles may not be covered
How Much Does DOL Insurance Cost?
DOL premiums are based on the total value of your inventory and the coverage limits you choose:
| Inventory Value | Typical Annual Premium | Per-Vehicle Cost |
|---|---|---|
| $100,000–$250,000 | $1,500–$2,500 | $30–$50/vehicle |
| $250,000–$500,000 | $2,500–$4,000 | $25–$40/vehicle |
| $500,000–$1,000,000 | $3,500–$6,000 | $20–$35/vehicle |
| $1,000,000–$3,000,000 | $5,000–$12,000 | $15–$30/vehicle |
| $3,000,000+ | $10,000+ | $10–$25/vehicle |
Key factors affecting your DOL premium:
- Total inventory value and number of vehicles
- Location (hail-prone areas cost more)
- Security measures (fencing, cameras, lighting)
- Claims history
- Deductible chosen (typically $1,000–$5,000 per vehicle, $25,000–$100,000 for catastrophic events like hail)
DOL Deductibles: Per-Vehicle vs. Catastrophic
DOL policies typically have two deductible levels:
- Per-vehicle deductible ($1,000–$5,000) — applies to individual vehicle losses like theft or collision. You pay this amount per vehicle before insurance kicks in.
- Catastrophic deductible ($25,000–$100,000) — applies to weather events (hail, flood, wind) that damage multiple vehicles at once. This higher deductible keeps premiums affordable for weather-related losses.
Choosing the right deductible is a balance between premium savings and your ability to absorb losses. Higher deductibles save on premium but require more cash on hand when a loss occurs.
DOL vs. Garagekeepers: What's the Difference?
This is one of the most common questions we get:
- DOL covers vehicles you own for the purpose of sale (your inventory)
- Garagekeepers covers vehicles customers own that are in your care (trade-ins, service vehicles)
Most dealerships need both. A used car lot with no service department might only need DOL. A repair shop with no inventory might only need garagekeepers. But if you have both inventory and customer vehicles on your property, you need both coverages.
Floorplan Lender Requirements
If you use floorplan financing (NextGear, AFC, Dealertrack, Ally), your lender almost certainly requires DOL coverage. Typical lender requirements include:
- DOL limit equal to or exceeding your credit line
- Lender named as loss payee on the policy
- Specific deductible maximums (often $1,000–$2,500 per vehicle)
- Proof of coverage before funding begins
Pro tip: If your lender increases your credit line, update your DOL limit immediately. A gap between your credit line and your DOL limit means you're self-insuring the difference.
Get Your DOL Quote
We work with multiple carriers experienced with dealers open lot coverage. Whether you have 10 vehicles or 1,000, we can find the right coverage at a competitive rate. Get your DOL quote here — same-day certificates available.
Disclaimer: Coverage details, limits, deductibles, and pricing vary by carrier, state, and individual risk characteristics. The cost ranges in this article are approximate and based on industry experience. This article is for informational purposes only and does not constitute a quote or guarantee of coverage. Consult a licensed insurance professional for advice specific to your business.
Kevin A. Smith
Kevin specializes in commercial insurance for automotive businesses — dealers, repair shops, towing companies, and garages — across FL, TX, GA, NC, SC, OK, NM, and UT. He works with 100+ A-rated carriers to find the right coverage at the right price.
View all articles by Kevin