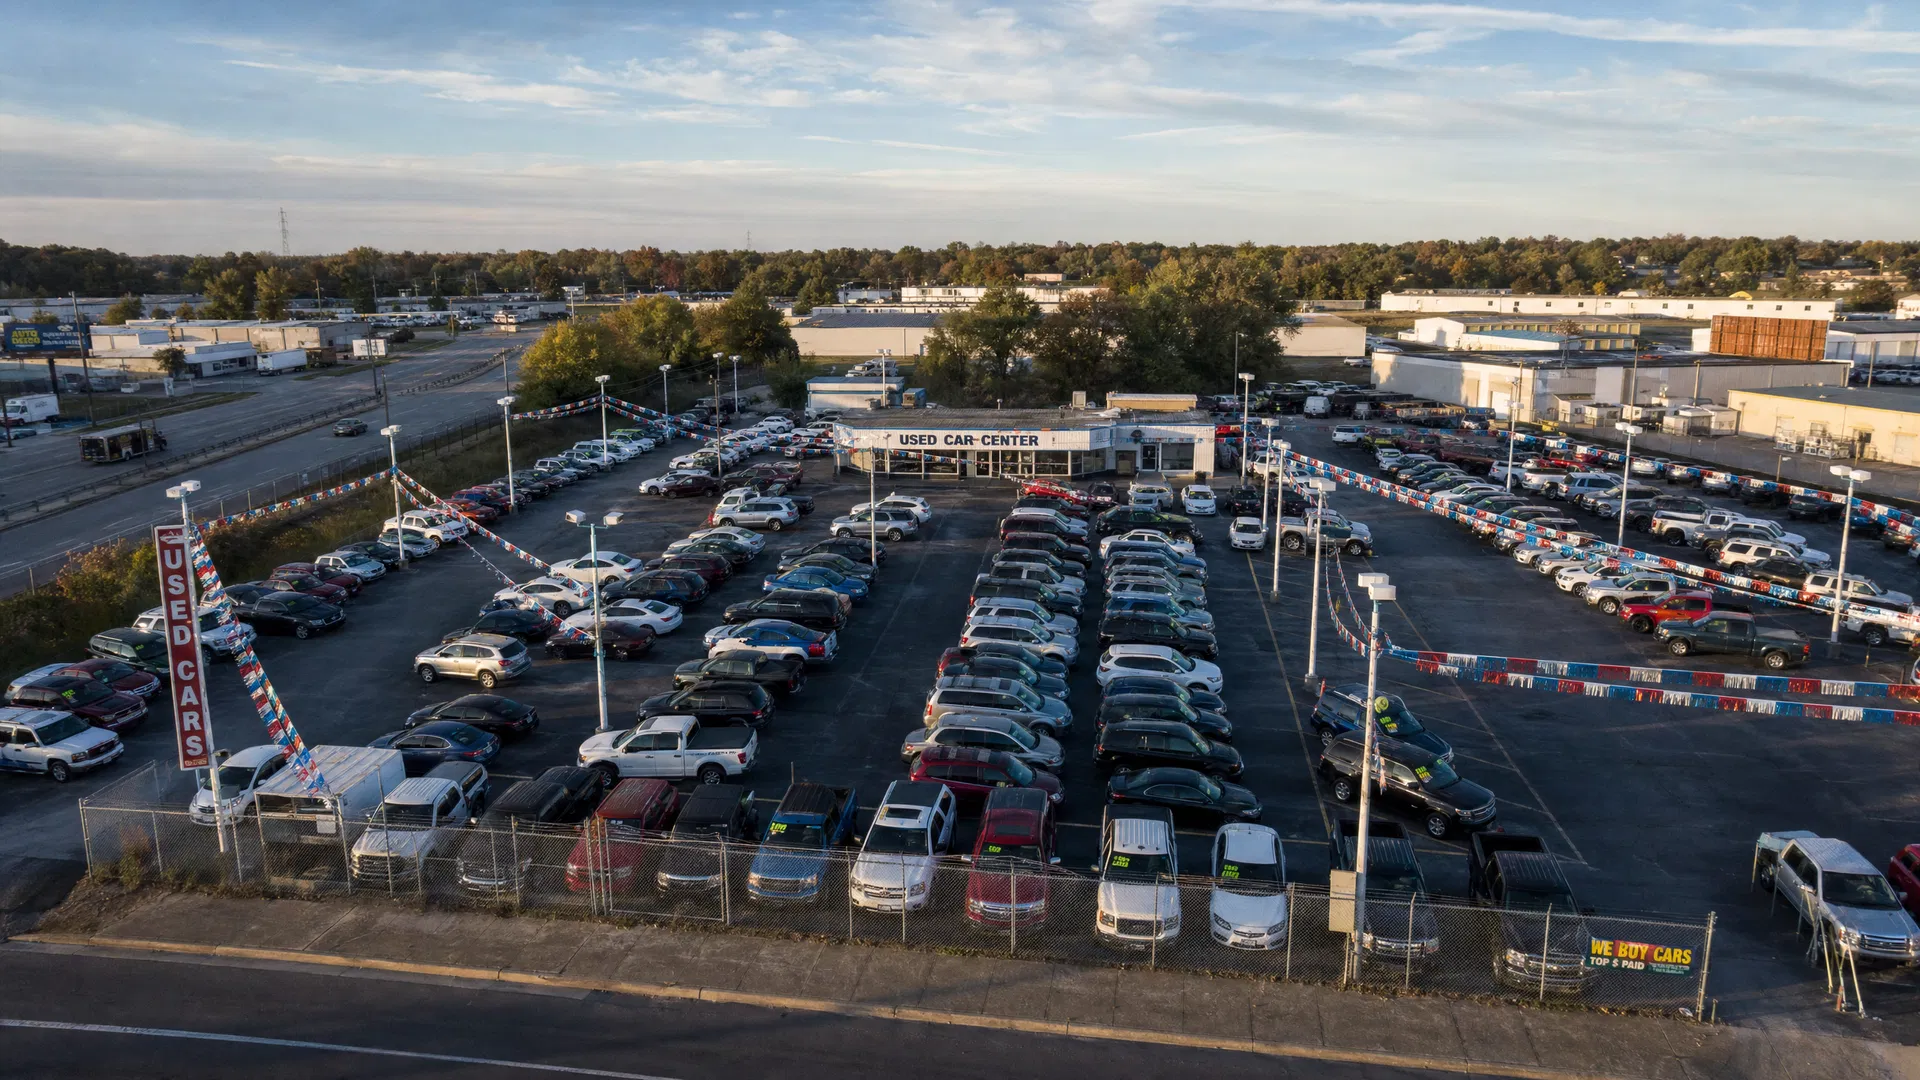
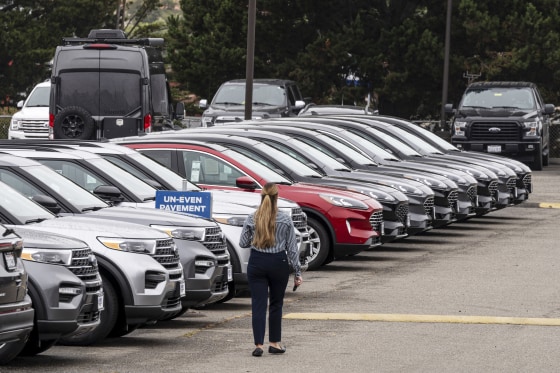
For auto dealerships, vehicle inventory represents the single largest asset on the balance sheet. A lot full of vehicles — whether new, used, or specialty — can represent millions of dollars in value sitting in the open air, exposed to weather, theft, and accidents every day. Dealers open lot coverage is the Insurance that protects this inventory, and it is one of the most important coverages in any dealership's insurance program.
What Is Dealers Open Lot Coverage?
Dealers open lot (also called dealers physical damage or auto dealers physical damage) is a form of property insurance specifically designed for vehicle inventory held by licensed auto dealers. It covers physical damage to vehicles in your inventory — vehicles you own and are holding for sale — against a broad range of perils.
Need a quote? Get an instant garage liability quote here — most businesses are quoted in under 60 seconds with same-day certificates available.
Unlike standard commercial property insurance, which covers buildings and business personal property, dealers open lot is specifically structured around the unique characteristics of vehicle inventory: it moves, it's stored outdoors, its value fluctuates, and it faces risks that standard property policies don't address.
What Does Dealers Open Lot Cover?
A standard dealers open lot policy covers physical damage to your inventory from:
- Hail and windstorm — One of the most common and costly perils for outdoor lots
- Fire and explosion
- Theft and vandalism
- Flood and water damage (check policy terms — some require separate flood coverage)
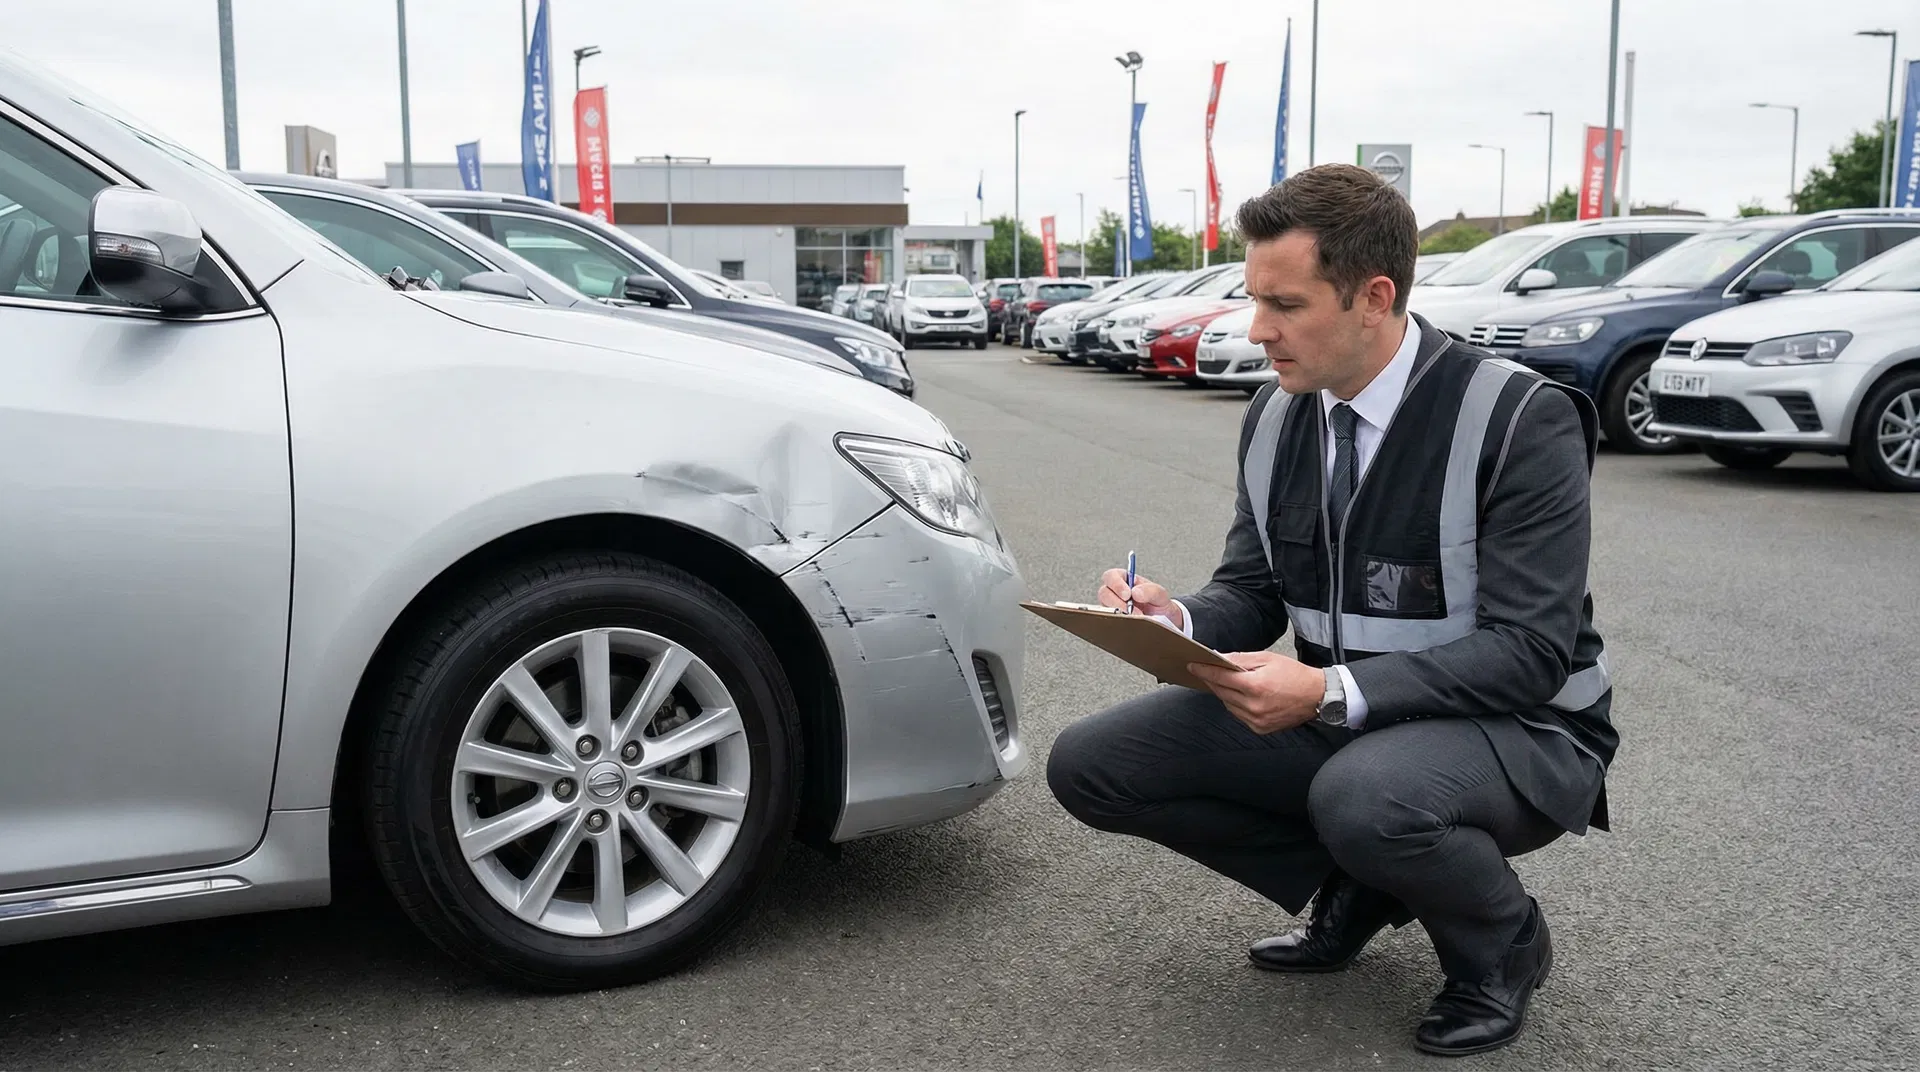
- Collision damage — Including damage from vehicles striking your inventory
- Riot and civil commotion
How Dealers Open Lot Differs from Standard Auto Insurance
Personal auto insurance and standard commercial auto insurance are designed for vehicles that are registered, titled, and driven regularly. Dealers open lot is designed for inventory — vehicles that are not yet titled to an end customer, may be moved infrequently, and are held primarily for resale. The rating structure, coverage terms, and claims process are all tailored to the dealer context.
One important distinction: dealers open lot typically does not cover liability arising from the use of those vehicles. That's the role of your garage liability policy. The two coverages work together to provide comprehensive protection for your dealership operations.
Setting the Right Inventory Limit
Dealers open lot policies are typically written on a reporting form or a blanket limit basis. Under a reporting form, you report your inventory value monthly and pay premium based on actual inventory. Under a blanket limit, you select a maximum coverage amount and pay a flat premium.
The key is ensuring your limit reflects your maximum inventory value — not your average. If your lot peaks at $2 million in inventory during your busy season, your coverage limit should be at least $2 million. Being underinsured at the time of a major loss means you absorb the difference out of pocket.
Floor Plan Lender Requirements
Most dealerships finance their inventory through a floor plan lender (a bank or finance company that provides a revolving line of credit secured by the vehicle inventory). Floor plan lenders universally require dealers to maintain dealers open lot coverage as a condition of the floor plan agreement. The lender is typically listed as a loss payee on the policy, meaning they receive payment directly in the event of a covered loss.
Failing to maintain adequate dealers open lot coverage is not just a financial risk — it's a breach of your floor plan agreement that can result in the lender calling the loan and demanding immediate repayment of the outstanding balance.
Additional Coverages to Consider
Beyond the core dealers open lot policy, dealerships should consider:
- Drive-other-car coverage for dealer principals and employees who use inventory vehicles as personal transportation
- Demonstration coverage for vehicles used for extended test drives or loaner programs
- Transit coverage for vehicles being transported to or from auctions, transport companies, or other locations
Working with a Dealer Insurance Specialist
Dealers open lot coverage is a product that not all insurance agents are equipped to place effectively. The right carrier, the right coverage form, and the right limit structure all matter significantly. At DealerLiability.com, we work with carriers who focus on auto dealer insurance and can build a program that properly protects your inventory investment. Get a free quote today.
Kevin A. Smith
Kevin specializes in commercial insurance for automotive businesses — dealers, repair shops, towing companies, and garages — across FL, TX, GA, NC, SC, OK, NM, and UT. He works with 100+ A-rated carriers to find the right coverage at the right price.
View all articles by Kevin